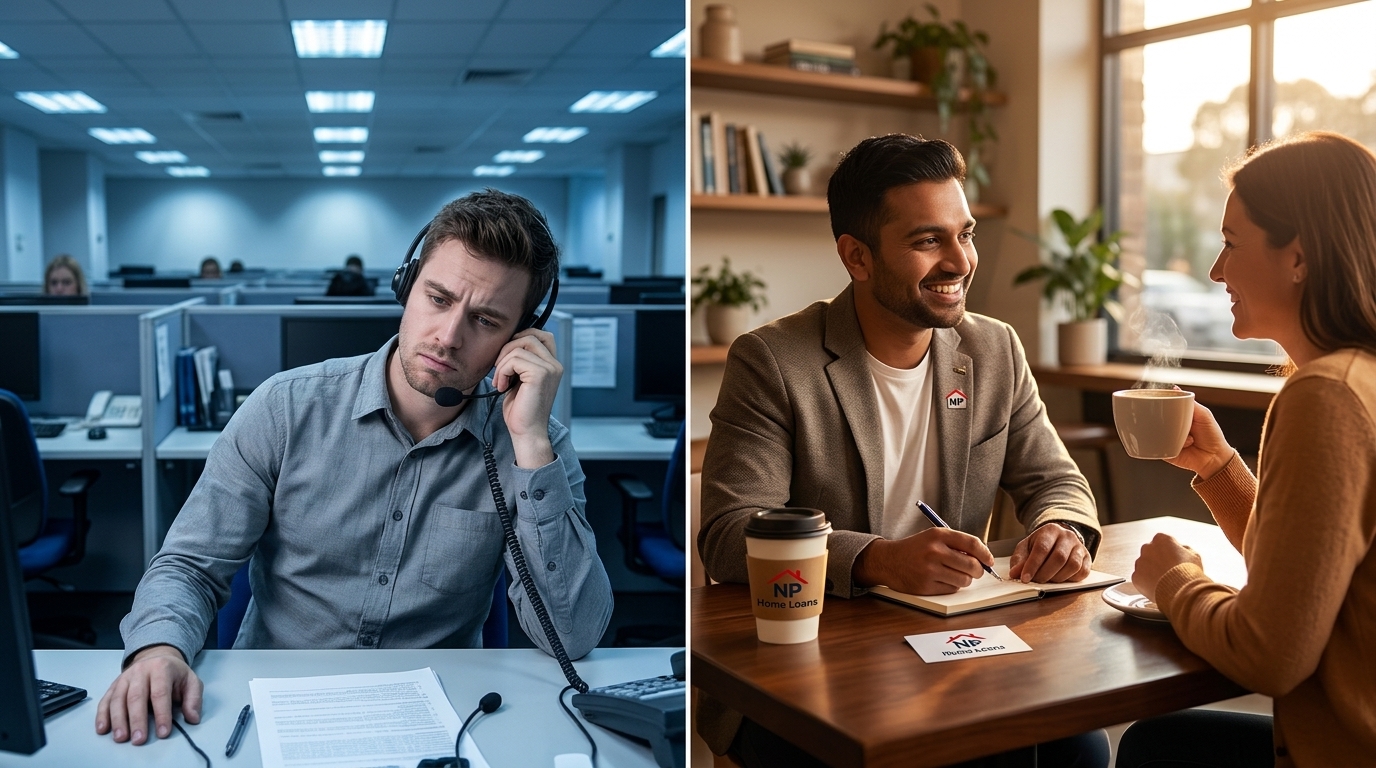
If you have ever tried calling your bank’s number during your lunch break in Mt Waverley or while grabbing a coffee near Chadstone Shopping Centre, you already know the story. You wait through twenty minutes of automated hold music, only to reach a call centre operator based states away or overseas reading straight off a script. When you ask why your variable interest rate has crept up while new customers get glossy discounts, you are given a generic answer and a reference number.
When it comes to the biggest financial commitment of your life, the real question is simple: Is a distant bank employee sitting in a call centre truly looking after your long-term interests, or are they just protecting their employer’s profit margin?
The Hidden Trap of Bank Call Centres
When you walk into a big four bank branch along High Street Road or apply through an online portal, the person handling your file works for the lender. Their duty of care is to the bank, not to you.
1. Limited Choice (The Single-Lender Constraint)
A bank officer can only offer you their own products. If their credit policy rejects your overtime income, self-employed earnings, or deposit structure, they cannot point you toward a lender with more flexible criteria. You get a firm “no” or an unfavorable structure.
2. High Turnover and Scripted Advice
Call centre representatives are evaluated on volume and call duration. You are rarely assigned a single point of contact. Every time you follow up on your pre-approval or unconditional approval, you explain your entire financial situation to someone new.
3. The “Loyalty Tax”
Big banks reserve their lowest rates and cashback incentives for new customers. Existing clients often quietly absorb incremental interest rate rises. Call centre staff will not proactively call you to lower your rate because doing so reduces their bank’s earnings.
Why Working with a Local Mt Waverley Mortgage Broker Changes Everything
Partnering with a local home loan specialist in Chadstone and Mt Waverley gives you a dedicated advocate whose legal obligation is to act in your best interests.
1. Legal Duty: Best Interests Duty (BID)
Under Australian credit legislation, mortgage brokers are bound by the Best Interests Duty (BID). Bank employees are legally exempt from this rule. A mortgage broker must prioritize your financial well-being, comparing hundreds of options to find a loan that fits your budget and lifestyle.
2. Access to 30+ Lenders Under One Roof
Rather than settling for one bank’s narrow criteria, a local broker compares options across major banks, regional lenders, and non-bank institutions. Whether you are buying your first unit near Monash University, upgrading to a family home in Mt Waverley, or refinancing an investment property in Chadstone, your broker shops around so you don’t have to.
3. One Direct Point of Contact
Instead of dialing a corporate call centre, you have a direct line to your local broker. At NP Home Loans, you speak directly with Nalin and the team—local experts who understand the Monash property market and guide your application from pre-approval through to settlement and annual reviews.
Comparison: Big Bank Call Centre vs. Local Broker (NP Home Loans)
| Feature | Bank Call Centre | NP Home Loans (Local Broker) |
| Legal Obligation | Works for the bank’s bottom line | Legally bound by Best Interests Duty (BID) |
| Product Options | 1 lender’s product suit only | 30+ lenders & 1,000+ loan options |
| Point of Contact | Different operator every call | Direct relationship with local specialist (Nalin & team) |
| Rate Monitoring | Rare (you pay the loyalty tax) | Proactive ongoing loan reviews & repricing |
| Local Knowledge | Generic national views | Hyper-local Monash & Mt Waverley market expertise |
Frequently Asked Questions (FAQ)
Does using a mortgage broker in Mt Waverley cost me money?
In almost all standard residential cases, no! The lender pays the broker a commission after your loan settles. You receive tailored expert advice, software-backed loan comparisons, and end-to-end management without paying an upfront consultation fee.
Will a local broker get me the same rate as going directly to a bank?
Often, a broker can secure a better rate. Brokers have direct access to internal pricing desks and negotiate discounts below advertised rates that front-line branch or call centre staff cannot offer.
Can a mortgage broker help if I’m self-employed or have complex income?
Yes. Bank call centres routinely struggle with complex tax returns, trust structures, or recent self-employed history. At NP Home Loans, we specialize in structuring your financials correctly to present a clear, low-risk application to the right lender.
Take Control of Your Mortgage Today
Stop leaving your financial future in the hands of an anonymous 1300 number. If you live or invest in Mt Waverley, Chadstone, or across Monash, contact NP Home Loans today for a complimentary rate check and borrowing capacity review.